Visakhapatnam Insurance: From a Policy Question to the Right Licensed Provider
Exclusions, claim status and settlement promises are the questions where an unchecked answer does the most harm. This guide is written for Insurance teams serving Visakhapatnam who want to explain policies from approved material and send enquiries to licensed providers. Read on for the details to collect, the local source to use, what an assistant is allowed to do and where a person approves the next step. Each workflow is meant for planning and does not describe a Brainguru client result. The scope of any service rests on your actual business, data and permissions.
Vizag on the Enquiry, Visakhapatnam on the Record
Many enquiries say Vizag, although the official district portal uses Visakhapatnam. Hold on to the alias for matching, and still identify the actual facility and the district it falls under. Avoid port-related wording that suggests your insurance business is a port operator or holds export approval.
Open Visakhapatnam district first. You can rely on it for local administrative context, but not as proof of market demand or commercial availability, nor as an endorsement of a private insurer. Enter the Visakhapatnam and Vizag alias with the facility district, and test that location against the approved business record. Disagreements go to a reviewer before any page or assistant gives directions, coverage information or an appointment instruction.
Fields for a Visakhapatnam Policy Enquiry Brief
A policyholder learns nothing from a city name sitting beside an unrelated national offer. Keep these fields as a working brief and tie each statement to where it came from and who reviewed it. Unavailable details are noted as gaps and passed to a person, so that no assumption comes from the model.
- Insurer/intermediary identity: Say which insurer or intermediary stands behind the policy, plus its real facility and district under the Visakhapatnam or Vizag name.
- Approved policy/product version: Give the current approved version of the policy or product, including what it does not extend to.
- Coverage, exclusion and eligibility information source: Identify where coverage, exclusion and eligibility wording comes from; missing wording is a review question.
- Servicing versus new-product enquiry: Decide whether the person holds a policy or wants a new one and file the approved evidence, because photographs and city names cannot decide that.
- Minimum contact permission: Take only the contact permission needed for the next step they asked for, and move unsupported or misrouted requests elsewhere.
- Authorised product/claims reviewer: List the authorised product or claims person who must confirm the answer before anything further is offered.
As an illustration, a Visakhapatnam request first has to pass the location check and the check on policy or product version. Until both are clear, nobody suggests a commercial or professional next step. Any failure is carried as an open item in the handoff, which gives the provider a concrete question and spares them a falsely qualified lead.
How Far an Insurance Assistant May Go
Keep the assistant’s job narrow. It retrieves the current approved policy explanation, distinguishes new-product questions from policy servicing and claims, and captures just what the handoff needs. The responsible insurer or authorised intermediary then confirms eligibility, terms and any recommendation. No automated marketing response should appear to approve a claim or give a final coverage decision.
The business decides which sources and systems may be connected, typically an approved knowledge pack, the relevant operational system and a CRM or intake route if needed. Log the version of the source for each answer. Run tests on access permissions and on who may revise policy content before touching live customer data. A draft, prediction or extracted field only assists the reviewer and creates no commercial commitment by itself.
Take a claim-status message as a planning example. A policyholder writes, "What happened to my claim?" This is servicing, and it should leave the marketing flow at once. The assistant does not look for the file or guess a stage. It gives the insurer's claims contact from the approved source, asks only for the policy reference the claims team needs to find the record and tells the person who will respond. The claims reviewer owns the reply from there. Nothing about the claim appears in any promotional follow-up, and the enquiry is counted as servicing, not as a lead.
Claims, Settlement and Suitability: Lines Not to Cross
Draw applicable product information from IRDAI resources and the responsible provider’s approved documents. Acceptance, claim settlement and savings must never be guaranteed. Health and financial documents must follow the provider’s approved process and stay out of a general city-page contact form. A testimonial or a local audience label cannot prove that a policy suits anyone.
Consult the Insurance Regulatory and Development Authority of India as your independent sector reference. Its current instructions should be read afresh, with the responsible professional reviewing how they apply to your proposed activity.
Telugu and English, Vizag Search Terms and Evaluation
Telugu and English are language options to think through with the business. They do not claim that every customer uses them, or that every translation comes from us. If the audience needs them, ask competent speakers to review terminology, locality names and the proposed next step. Use one actual address and contact route across page and business records, and never create extra offices or profiles for the sake of a local presence.
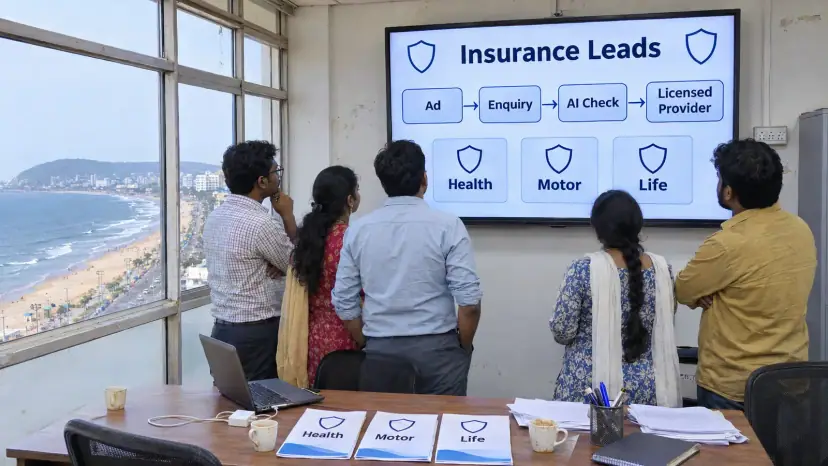
For Visakhapatnam enquiries, note where the audience is and, separately, where the requested service is fulfilled. Write the page and route each policy enquiry from the approved serviceable area. Measure the stages on their own: policy question → product/servicing triage → authorised reviewer → agreed application or service step. Rejected, cancelled and unsupported requests are part of the evaluation too, as a click or conversation never equals revenue.
Your test list should have an exclusion question, an outdated policy version, a claim-status enquiry and someone asking for guaranteed settlement. Weigh the reviewed outcomes against the business’s baseline before you raise spend. Mismatched intent in search queries shows which answer or handoff to improve. You will get no guarantee from us on rankings, inclusion in AI answers, lead volume or return on investment.
Settle who owns what. The product owner keeps the approved policy explanations current and withdraws old versions. The claims lead owns anything about claim handling. The compliance reviewer owns wording limits. When a policy version changes and no one tells the assistant's content owner, customers are quoted terms that no longer apply, and the first sign is a complaint to the claims team.
Next Reading for Vizag Insurance Teams
The scope for this industry is on Insurance solutions. For implementation, turn to AI Claims Document Processing: Workflow, Data Requirements and Human Review, keeping in mind that it explains a related workflow and is no evidence of a Visakhapatnam client engagement.
Consider BFSI (Banking & Finance) and Healthcare if you have other planning tasks in the city. The Visakhapatnam and other city guides page compares supported information and official references.
Arrive at your free consultation with the insurer or intermediary identity, the approved policy or product version, approved source material and the reviewer who can decide what comes next. Our delivery comes out of Noida and no Visakhapatnam branch is claimed. We take scope, integrations and on-site work case by case.
Everything linked here was checked on 5 October 2026, and current instructions should be checked again before campaign changes. Photos are illustrative topic images and do not verify local offices, customers or facilities.